
A client can find their next property before their existing home has sold, creating a timing gap that needs a practical lending solution.
Bridging finance can give brokers another way to manage the transition, helping eligible clients secure their next property while they complete the sale of their existing home.
MA Money Bridging Loans offer peak debt of up to $5 million, 6 to 12 month terms, capitalised interest, Full Doc and Alt Doc options and flexibility around the end debt.
The expanded lending capacity also creates more scope for larger buy before sell scenarios, including self-employed clients who may benefit from an Alt Doc assessment.
In this article
- How MA Money Bridging Loans work: Key features and policy settings to consider when structuring a buy before sell scenario.
- More scope for larger bridging scenarios: How the higher maximum loan size can support clients with larger peak debt requirements.
- Supporting self-employed borrowers: How Alt Doc can provide an income verification option for eligible clients with shorter business histories.
- Real scenario – A $4 million purchase: See how bridging finance and Alt Doc could work together for a self-employed dentist buying before selling.
How do our Bridging Loans work?
MA Money’s Bridging Loans are designed for clients who need to purchase their next property before their existing property has sold.
The loan can accommodate peak debt from $200,000 up to $5 million, with lending available up to the applicable maximum LVR and loan terms of 6 to 12 months. Interest can be capitalised for up to 12 months, helping clients manage cash flow while they complete the sale of their existing property. Once the existing property is sold, the sale proceeds are used to reduce the bridging debt and establish the applicable end debt.
For brokers, the starting point is understanding the client’s full property position, including the existing property value, current debt, new purchase price and expected sale position.
What are the key features of an MA Money Bridging Loan?
Here’s our current Bridging Loan policy:
| Loan sizes | $200,000 to $5 million (peak debt) |
| Maximum LVR | Up to 80% |
| Loan term | 6 to 12 months |
| Income verification | Full Doc and Alt Doc |
| Interest | Capitalised interest available |
| End debt | With no end debt, no income serviceability assessment is required. The proposed exit strategy, such as proceeds from the sale of the existing property will be assessed to confirm it is a realistic source of repayment. |
| Cash out | Available to maximum LVR, subject to criteria |
| Clawbacks | None |
These settings give brokers scope to assess the complete scenario, including the client’s existing property, proposed purchase, income position and expected end debt. As per all of MA Money’s loans, there’s no credit scoring, CCR or DTI requirements, subject to lending criteria.
What does the higher bridging loan size mean for brokers?
The ability to consider peak debt of up to $5 million gives brokers more scope to structure larger buy before sell scenarios.
This can be particularly relevant when a client is upsizing into a higher-value property, where the temporary peak debt is significantly higher than the debt they expect to retain after selling their existing home.
Looking at the client’s overall property position, including the proposed purchase, existing mortgage and expected sale can help brokers assess how the scenario fits within the available lending parameters.
The expanded lending capacity can also be relevant for self-employed borrowers where the income verification pathway needs to be considered alongside the bridging structure.
How can Alt Doc support self-employed bridging clients?
MA Money offers Alt Doc income verification for eligible self-employed Bridging Loan applicants.
An Alt Doc application requires a Declaration of Financial Position plus one income verification document. This can be an Accountant Letter, six months BAS or six months of business bank statements.
For a client who has recently moved from PAYG employment into running their own business, this can provide another way to demonstrate their current income position where a longer history of traditional financial documentation is not available.
For Near Prime self-employed borrowers, MA Money’s current Bridging Loan information specifies an ABN history of more than 12 months and GST registration of more than six months, subject to the applicable lending criteria.
That can be useful when a client’s relatively recent move into self-employment forms part of a broader buy before sell scenario.
Example: buying a $3.2 million home before selling
Consider a dentist who established their own practice 12 months ago after several years as a PAYG employee.
Their partner is a PAYG professional, and the couple have recently welcomed their third child. They want to move into a larger family home and have found the right property, but their existing home has not yet sold.
The number looks like this:
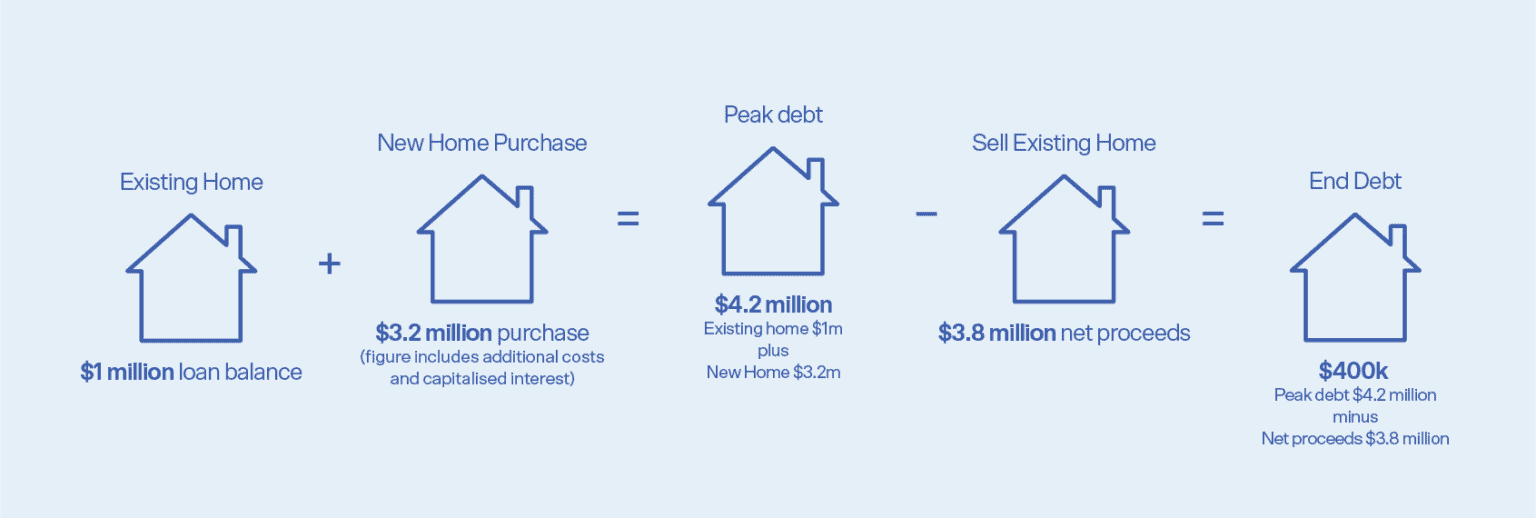
The clients want to secure the $3.2 million property before selling their existing home. At the same time, the dentist’s relatively short self-employed history means the income verification approach needs to be considered as part of the application.
A Near Prime Bridging Alt Doc structure provides a pathway to consider both parts of the scenario.
The bridging structure addresses the timing between purchasing the new property and selling the existing home. The Alt Doc assessment provides an income verification option suited to the dentist’s shorter self-employed history.
With our recent policy updates, Near Prime Bridging Alt Doc is now available for loans up to $5 million at 80% LVR, previously $2 million. This means the $3.2 million purchase can be considered within the expanded lending parameters.
The example shows how the increased loan size can create more room for brokers working with higher-value clients, while the availability of Alt Doc provides another option for eligible self-employed borrowers.
What should brokers consider when structuring a bridging scenario?
Start with the two properties and work through the client’s position before and after the existing property is sold.
Current property values, existing debt, the new purchase price and a realistic expected sale position will help establish the likely peak debt and end debt. It’s also worth considering the proposed bridging term, with capitalised interest included in the peak debt amount.
For self-employed borrowers, check the client’s ABN and GST history early and decide whether Full Doc or Alt Doc is the appropriate income verification pathway.
A well-packaged submission gives credit a clearer picture of the client, the properties, the purpose of the lending and the expected exit from the bridging facility. MA Money BDMs can help brokers work through the structure before submitting an application. We offer a 48-hour turnaround from submission to conditional approval, helping you move quickly when timing matters.
Got a buy before sell scenario?
If your client has found their next property while their existing home is still to be sold, a Bridging Loan could give you another way to structure the deal.
MA Money Bridging Loans support peak debt of up to $5 million, with Full Doc and Alt Doc options, 6 to 12 month terms, capitalised interest and flexible end debt.
Speak with your BDM about the scenario or use the MA Money Bridging Calculator to work through your client’s position.
Information for broker use only. This article is of a general nature only, does not constitute financial, tax, legal or credit advice, and does not take into account the personal objectives, financial situation or needs of any individual. It does not constitute credit assistance as defined under the National Consumer Credit Protection Act 2009 (NCCP Act). Brokers are independently responsible for complying with all applicable obligations under the NCCP Act. You should seek independent advice from a licensed professional before making any financial decisions. Applications for credit are subject to eligibility and lending criteria. Fees, charges and T&Cs apply (available on request). MA Money Financial Services Pty Ltd ACN 639 174 315 Australian Credit Licence 522267.
